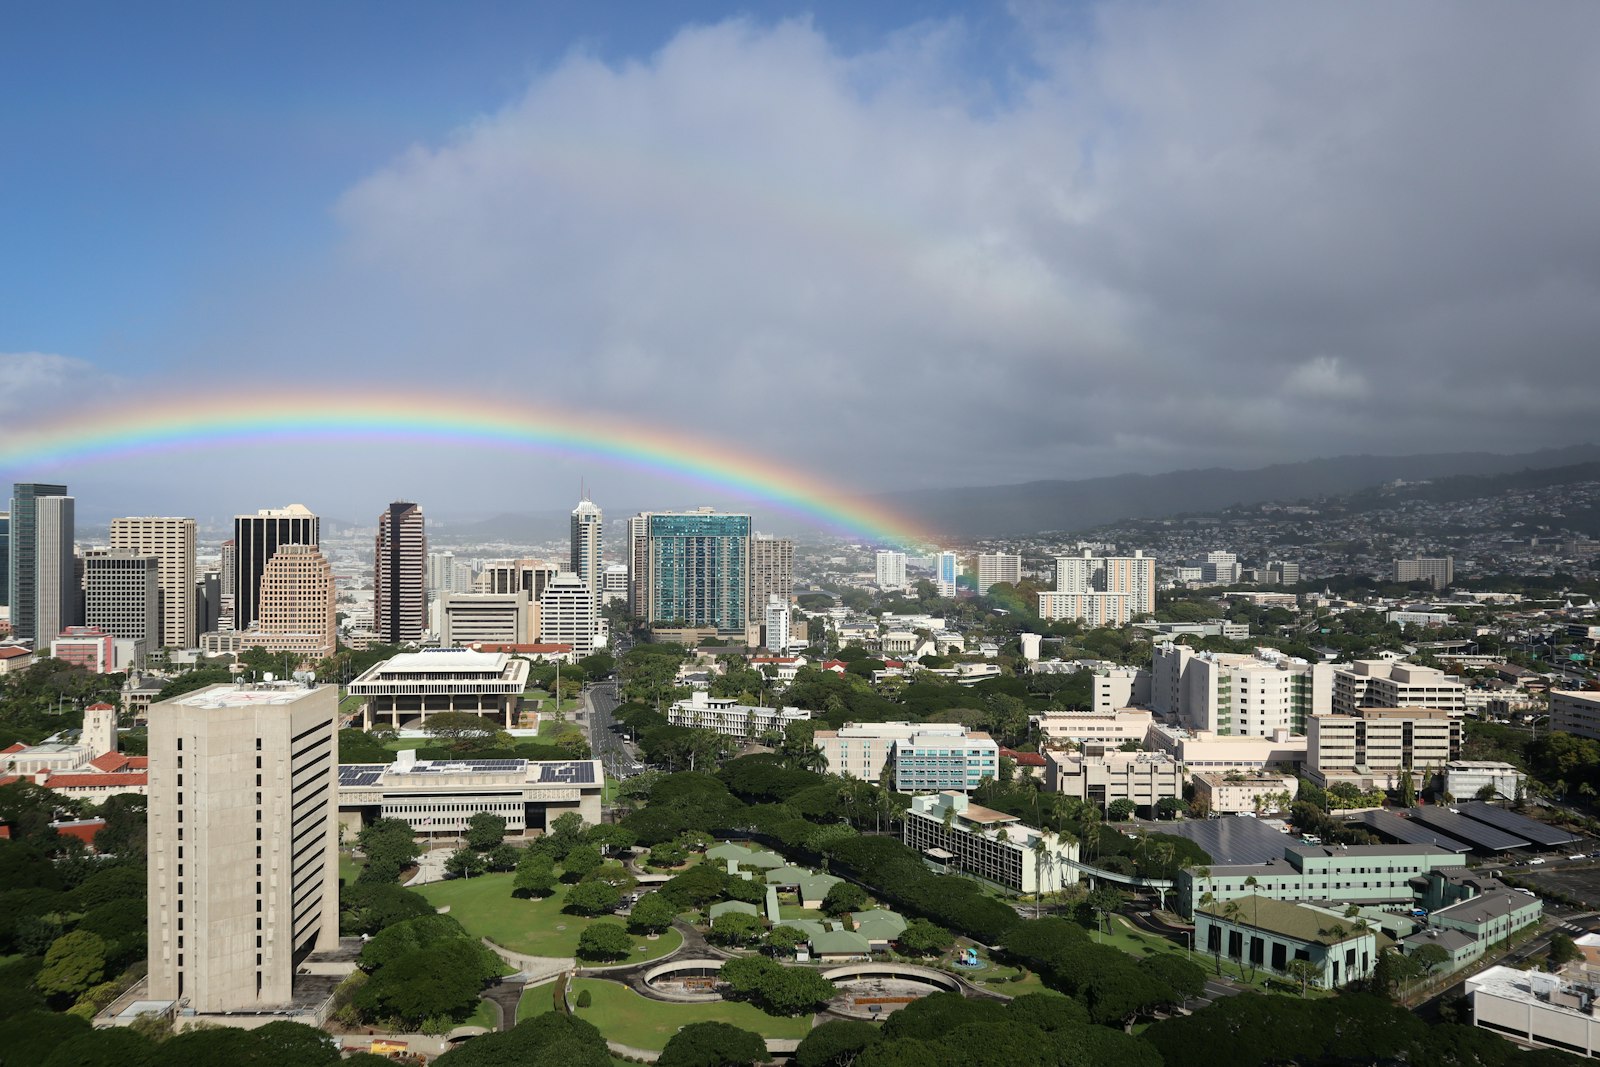
In June 2026 the median price of a single-family home on Oahu hit a record $1,242,500. That number matters more than it looks. The point where a mortgage stops being a normal "conforming" loan and becomes a jumbo loan in Honolulu this year is $1,249,125. By September the median had eased to $1,110,000, but the typical Oahu house is still selling within shouting distance of the point where financing changes gears.
I've been writing contracts here for 20+ years, and jumbo financing used to be a luxury-buyer conversation. Now it comes up on ordinary three-bedroom homes in Mililani and Kaneohe. If you're buying on this island, there's a real chance you'll touch jumbo territory, so it's worth understanding before you fall in love with a listing.
Where the jumbo line actually sits in Hawaii
A conforming loan is one that Fannie Mae or Freddie Mac will buy, which keeps rates and terms standardized. Each year the Federal Housing Finance Agency (FHFA) sets the ceiling. For 2026 the national baseline is $832,750 for a one-unit home. Hawaii, Alaska, Guam, and the U.S. Virgin Islands get a special statutory bump to 150% of that figure because building here costs so much.
That puts Honolulu County's 2026 one-unit conforming limit at $1,249,125. Anything you borrow above that is a jumbo loan. Maui and Kalawao counties run a little higher at $1,299,500. A couple of quick notes so nobody gets tripped up:
- The limit is on the loan amount, not the purchase price. Put enough down and a $1.5M home can still be financed with a conforming loan.
- Two-, three-, and four-unit properties have higher limits, which matters if you're buying a home with an ohana unit or a small multifamily.
- If you've seen an older figure like $625,500 floating around, that's years out of date. The limit has climbed a lot.
FHFA usually announces the next year's limits in late November, so check for the 2027 figure if you're closing in the new year. Our financing overview walks through loan types more broadly if you're just getting oriented.
Why so many Oahu buyers cross it
With the single-family median between about $1.1 million and $1.25 million for most of 2026, a large share of Oahu house sales land near or above the point where jumbo financing comes into play, depending on how much you put down. In the higher-priced areas it's nearly every sale. A single-level home in Kahala, a marina property in Hawaii Kai, or a view home up on Wilhelmina Rise is almost always a jumbo loan unless the buyer is bringing a large down payment or paying cash.
This isn't a reason to panic. It just means the financing conversation needs to happen early, because jumbo loans are underwritten more carefully than conforming ones.
What lenders look for on a jumbo loan
There's no single rulebook. Jumbo loans aren't bought by Fannie and Freddie, so each lender sets its own guidelines and they vary quite a bit. That said, these are the areas every jumbo lender looks at, and the requirements tighten as the loan gets bigger:
- Down payment: usually more than a conforming loan requires, and more again as the loan size climbs.
- Credit score: minimums are set by each lender and tend to be higher than for conforming loans. The best pricing shows up with strong credit.
- Debt-to-income: each lender sets its own cap, and a strong file with reserves gives you more room.
- Cash reserves: this is the one that surprises people. Lenders often want months of mortgage payments in the bank after closing, and more on larger loans.
- Appraisals: on bigger loan amounts, some lenders require two separate appraisals.
None of this is meant as a quote for your situation. Guidelines move, and the right loan depends on your income, assets, and the specific property. A good local lender will run your actual numbers. If you'd like introductions to lenders who do a lot of jumbo volume here, I'm glad to make them.
Military and VA buyers may not need a jumbo at all
This is one of the most useful things I can tell a PCS or veteran buyer, and a lot of people don't know it. A veteran with full VA entitlement has no loan limit in 2026. You can buy above $1,249,125 with $0 down, because the VA guarantees the lender's position regardless of the amount. The county conforming figure only comes back into the picture if your entitlement is partial, meaning you already have a VA loan in place or previously defaulted. In that case, the zero-down amount is tied to the county limit and you may need a down payment only on the portion above it.
The exact partial-entitlement figure can lag the conforming number on some published tables, so confirm it with your lender before you write an offer. But for a first-time VA buyer with full entitlement, a high Oahu price tag is not the obstacle people assume it is.
Condos carry an extra layer
A jumbo loan on a condo isn't just about you. The lender also underwrites the building. They'll look at the AOAO's budget and reserves, owner-occupancy ratios, any pending litigation, and how much of the building operates as short-term vacation rentals. A unit in a project that's mostly transient-rental or that has thin reserves can be harder to finance even when the buyer is rock solid. This is where knowing the individual buildings matters, and it's a big part of what my team tracks.
Frequently asked questions
What is the jumbo loan limit in Honolulu for 2026?
$1,249,125 for a one-unit home. Borrow above that and you're in jumbo territory. The limit is on the loan, not the price, so your down payment affects whether you cross it.
Do jumbo loans have higher interest rates?
Not always. For years jumbo rates actually ran a touch below conforming, and lately they've been close to even. For reference, Freddie Mac's conforming 30-year average was 7.40% the week of October 15, 2026. It moves around, so I won't quote you a number that'll be stale next week. Ask your lender for a same-day comparison on both.
How much do I need to put down on a jumbo in Hawaii?
Depends on the lender and the loan size, and the required down payment generally rises as the loan grows. Get quotes from more than one lender that does jumbo loans regularly. Strong credit and good reserves give you the most options.
Can I use a VA loan on a home over the conforming limit?
Yes, if you have full entitlement, with $0 down and no cap. If your entitlement is partial, the county limit applies and you may owe a down payment on the amount above it. Confirm your entitlement status with your lender first.
Is it harder to get a jumbo loan on a condo here?
It can be. The lender underwrites the building as well as you, so reserves, owner-occupancy, litigation, and the vacation-rental mix all factor in. Some buildings finance easily and some don't. I'd check the specific project before you get attached to a unit.
This is general information from a licensed real estate broker, not legal, tax, insurance or financial advice. Rules and figures change, so confirm anything that affects your decision with the right licensed professional.
Sources: FHFA 2026 conforming loan limits, HBR June 2026 report, Honolulu Board of REALTORS, September 2026 Oahu market report, Freddie Mac Primary Mortgage Market Survey, VA home loan limits
Tony Kawaguchi, R(B), The Kawaguchi Group, eXp Realty. Hawaii broker, license RB-21841, 20+ years and $1B+ in Oahu sales, leading a team of 20+ agents.
Thinking about a higher-priced home on Oahu?
The financing piece is very solvable here, but it rewards planning. If you want to understand your options before you start touring, I'll connect you with lenders who do real jumbo volume on this island and help you line the financing up with the right property. Reach out to me here, or start with our buyer resources to get oriented.